Truckload Linehaul Rates Surge While August Shipment Volumes Mark Historic Inflection Point

Truckload linehaul rates maintained their upward trajectory in August, registering another substantial gain as shipment counts turned positive for the first time in three and a half years, according to comprehensive market data released by Cass Information Systems.
The Cass Truckload (TL) Linehaul Index, a primary logistics benchmark tracking rates excluding fuel and accessorial surcharges, jumped 11.3% year over year in August. This performance represented a 70-basis-point increase compared to July metrics. Most notably, the August reading extended an unprecedented streak of 20 consecutive year-over-year rate increases, marking the steepest upward acceleration recorded since June 2022. While the index encompasses for-hire spot rates, it remains historically weighted toward long-term contract rates, serving as a reliable bellwether for structural pricing shifts across the broader domestic freight transportation ecosystem.
Market Dynamics: Contract Pricing Adjusts Higher
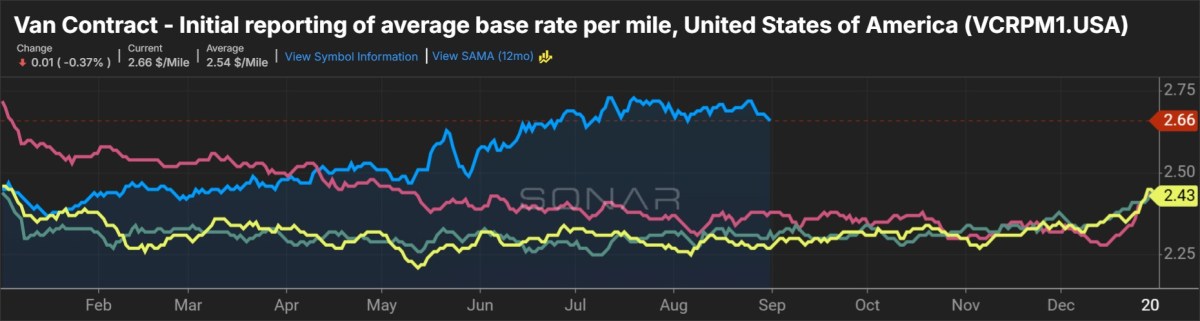
Market analysts note that the sequential increase observed in August aligns directly with underlying expectations set by spot market behavior earlier in the year. Although transactional spot market rates experienced a mild sequential cooling period, the vastly larger contract market continued to adjust upward. This upward pressure on contract pricing reflects enduring capacity constraints, stricter regulatory compliance enforcement targeting non-compliant operators, and rising operational overhead for carriers nationwide.
Data derived from freight bills processed by Cass Information Systems—which manages approximately $37 billion in annual freight payables—highlights a persistent escalation in TL contract rates even as macroeconomic demand indicators remain relatively subdued. Industry observers suggest that these pricing adjustments are necessary to absorb increasing insurance premiums, equipment replacement costs, and maintenance expenses that have squeezed carrier margins over the prolonged freight recession.
A Historic Inflection Point for Shipment Volumes
For the broader transportation network, August delivered a long-awaited milestone. Freight shipment volumes recorded by Cass increased by 2.1% year over year. This expansion breaks a grueling 42-month consecutive decline that began during the post-pandemic market correction. On a sequential basis, August shipments surged 5.6% higher than July levels, translating to a 5.0% increase when adjusted for seasonal factors.
While the Cass index encompasses all domestic transportation modes, truckload sectors account for more than 50% of the total tracked shipments, while less-than-truckload (LTL) operations represent roughly 25%. Analysts observed that road-to-rail conversion trends have exerted noticeable downward pressure on trucking-centric datasets in recent months, largely driven by surging fuel costs that frequently incentivize shippers to pivot toward intermodal alternatives for long-haul routes.
Despite these modal shifts, normal seasonal shipping patterns, if sustained through September, are projected to keep the index hovering around a 1% year-over-year increase, signaling a stabilization of baseline freight activity.
Escalating Freight Expenditures and Fuel Pressures
Driven by the positive inflection in shipment volumes and sharp spikes in diesel prices, the Cass Expenditures Index surged dramatically. The index, which measures total freight spend inclusive of fuel surcharges, climbed 18.7% year over year in August. Sequentially, total expenditures rose 5.8% from July, or 6.0% on a seasonally adjusted basis.
This expenditure growth was heavily exacerbated by energy markets. Diesel prices surged approximately 46% year over year and rose roughly 10% sequentially during the same window. These fuel cost escalations compounded the financial burden on shippers, amplifying total logistics costs even in an environment where consumer demand growth has shown signs of moderation.
Economic Context and Forward-Looking Outlook
Looking toward the remainder of the year, the Cass report strikes a cautiously optimistic tone while acknowledging elevated risks tied to consumer spending and a soft labor market. However, several macroeconomic catalysts point toward a more durable demand floor.
"With economic growth strong even amid a soft job market, and a restock likely beginning with ocean volumes rising and tariff refunds happening, the bottom is probably in," the Cass report stated. "While likely modest, freight growth should continue."
This sentiment suggests that inventory destracking cycles have largely run their course across many retail and manufacturing supply chains. As ocean import volumes recover and corporate replenishment cycles initiate ahead of the fourth-quarter peak shopping season, truckload demand is expected to experience steady, if measured, expansion.
Broader Implications for Shippers and Carriers
The August data release underscores a critical juncture for supply chain executives and transportation providers. The simultaneous rise in contract linehaul rates and the return of positive year-over-year volume growth confirm that the U.S. freight market has transitioned out of its prolonged contraction phase.
For shippers, the data signals that the era of deeply discounted truckload capacity has officially concluded. Securing reliable capacity will increasingly require competitive contract pricing and collaborative shipper-carrier relationships, particularly as regulatory bodies continue to crack down on non-compliant carriers and unsafe operations.
For motor carriers, the numbers offer validation of disciplined capacity management and resilience through a historic multi-year downturn. As operating costs remain elevated and compliance standards tighten, carriers that successfully navigated the freight recession are finding themselves positioned with enhanced pricing power as volume demand gradually returns to historical baselines.