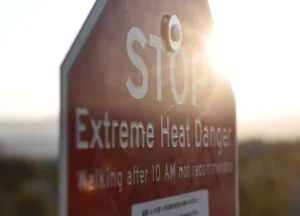
The data, derived from the GEA’s latest sentiment survey on global electronics manufacturing, reveals that nearly 40% of manufacturers worldwide have already grappled with heat-related operational interruptions in 2026. For an industry that relies on precision timing and delicate semiconductor fabrication processes, the implications are severe. As temperatures climb, the strain on cooling infrastructure, electrical grids, and logistics networks has created a complex web of vulnerabilities that firms are struggling to mitigate.
The Anatomy of Supplier Disruptions
The most acute impact cited by survey respondents is the disruption of supplier fulfillment. Almost 50% of manufacturers surveyed noted that the flow of components and raw materials has been hindered by extreme heat, with the effects felt most sharply across the major industrial hubs of North America, Europe, and Asia. While the survey did not categorize every specific failure point, industry experts suggest a cascading effect.
Shawn DuBravac, Chief Economist for the association, noted that these delays are likely the result of a "perfect storm" of stressors. "My sense is that it was probably an assortment of different things that would fall under that broader category of supplier delays," DuBravac explained. These include labor shortages caused by unsafe working conditions in non-climate-controlled facilities, factory-level power constraints that force reduced shifts, and broader freight and warehouse bottlenecks where heat-sensitive transport protocols have slowed the velocity of goods.
In many instances, the "just-in-time" delivery model—a cornerstone of the electronics industry—has proven fragile in the face of record-breaking heat. When a primary supplier in a high-temperature zone faces a 48-hour shutdown due to grid instability, the ripple effect can bring assembly lines thousands of miles away to a complete halt.
Chronology of Escalating Climate Risks
The 2026 findings are the culmination of a multi-year trend. For the past decade, climate scientists and meteorologists have warned that industrial zones would face increased "wet-bulb" temperature events—conditions where high humidity and heat make it physically impossible for humans to work outdoors and for cooling systems to effectively dissipate heat from machinery.
By 2023, early indicators of this trend began appearing in corporate ESG (Environmental, Social, and Governance) reports, with firms mentioning "extreme weather" as a growing risk factor. By 2025, the narrative shifted from theoretical risk to active disruption. This year, the frequency of heat-induced alerts for industrial zones has reached a decadal high, forcing the GEA to prioritize climate resilience in its annual industry sentiment analysis. The current data reflects a turning point where heat is no longer viewed as an "act of God" insurance clause, but a standard variable in supply chain risk management.
Regional Breakdown: The North American Context
While the global perspective is alarming, the data for North America provides a nuanced look at how regional infrastructure is coping. According to the GEA, 20% of North American firms reported minor disruptions, and 57% reported no major issues—a statistic that suggests some level of insulation due to more robust climate-controlled facility standards. However, 6% of firms reported major interruptions, and another 6% faced moderate challenges.
More concerning is the "exposure" metric. Nearly half of North American manufacturers (47%) acknowledged that their supply chains are currently exposed to severe heat-related risks. Even those who have avoided significant downtime are reporting high levels of anxiety regarding future capacity.
The primary concerns for these firms include:
- Cooling Limits: 29% of respondents identified the inability of current HVAC and cooling infrastructure to handle ambient heat as a top-tier bottleneck.
- Power Reliability: 29% cited grid curtailments and potential power outages as a significant threat to continuous operations.
- Transportation and Logistics: 17% expressed concerns over heat-related slowdowns in the movement of goods, including potential damage to sensitive electronic components in transit.
Productivity and Operational Throughput
The human and mechanical toll of the heat cannot be overstated. Among manufacturers worldwide who reported heat-related disruptions, more than 80% confirmed a negative impact on productivity. In North America, the figures show that 13% of firms suffered major operational setbacks, while 50% reported moderate impacts that required active intervention.
"To me, a moderate impact would be something that has to be addressed, something that impacted throughput, that impacted production schedules," DuBravac said. These moderate impacts often manifest as mandatory mid-day work stoppages, the slowing of machine cycle times to prevent overheating, and the frequent maintenance of equipment that is running outside of its optimal thermal envelope.
The survey further highlights that firms are bracing for a future where these conditions become the new normal. Over two-thirds of global manufacturers expect to face recurring heat-driven productivity dips in the coming years. In North America, while the expectation of major disruption is lower than the global average, there is a widespread acknowledgment—32%—that minor, consistent heat-related productivity losses are now an anticipated line item in their five-year operational forecasts.
Strategic Implications and the Case for Contingency Planning
The findings suggest that the electronics industry is at an inflection point. For decades, the focus has been on optimizing costs and lead times. Now, the mandate is shifting toward climate-hardened supply chains.
Industry analysts suggest that the fall, when ambient temperatures begin to drop, is the most critical period for manufacturers to reorganize their operational strategies. Relying on reactive measures—such as temporarily increasing staff or fast-tracking air freight—is proving unsustainable and prohibitively expensive. Instead, the focus is shifting toward "scenario planning."
DuBravac suggests that companies must adopt a "playbook" approach. "If I were advising a manufacturer, I would tell them now is the perfect time to run scenario plans on what happens to your operations if you had a week of 110-degree weather, if you had two weeks of 110-degree weather, if you had three weeks of 110-degree weather," he stated.
The proposed playbook should include:
- Redundancy in Sourcing: Moving away from single-source suppliers in regions with high climate volatility.
- Infrastructure Hardening: Investing in onsite power generation, such as microgrids or battery storage, to bypass regional grid failures during heat-induced peak demand.
- Climate-Adaptive Logistics: Integrating meteorological data into supply chain management software to proactively reroute shipments before extreme weather events materialize.
- Operational Flexibility: Redesigning shifts to take advantage of cooler night hours or automating high-heat production zones that are difficult for human workers to staff during extreme temperature spikes.
The Path Forward
The data from the Global Electronics Association serves as a wake-up call. As the electronics industry continues to underpin nearly every aspect of the modern economy—from consumer hardware to automotive and aerospace components—the fragility of its supply chain is a systemic risk.
The fact that 50% of manufacturers in major regions are already seeing material disruptions indicates that the "heat tax" is already being paid in the form of missed targets and inflated operational costs. Moving forward, competitive advantage will likely belong to those firms that stop treating heat waves as anomalies and begin integrating them into their core logistical, financial, and architectural frameworks.
As the industry enters the next cycle of production, the focus will inevitably shift from simply identifying these risks to executing the massive capital expenditures required to harden facilities and diversify supplier networks. For the electronics sector, the lesson of 2026 is clear: when the climate shifts, the supply chain must move with it, or risk being left behind in the heat.