Disney Reveals Ambitious Growth Strategy With Projected $26 Billion Content Spend for Fiscal 2027

The Walt Disney Company has signaled a massive escalation in its financial commitment to content creation and distribution, projecting a cash content spend of approximately $26 billion for fiscal 2027. This figure represents a substantial 9% increase compared to the anticipated expenditures for fiscal 2026. The aggressive spending outlook was officially detailed in the entertainment conglomerate’s fiscal fourth-quarter earnings report, which was released on Tuesday.
The forward-looking financial projection comes on the heels of a triumphant financial period for the House of Mouse. Disney soundly surpassed Wall Street’s consensus earnings estimates for the fourth quarter, delivering robust financial and operational results across nearly all major business segments. The company’s film studios, television production units, direct-to-consumer streaming division, and global portfolio of theme parks all contributed to the better-than-expected quarterly performance, reinforcing executive confidence in the company’s multi-year strategic roadmap.
However, it is the clear acceleration of capital deployment into content—encompassing premier sports rights, Hollywood feature film slates, and an aggressive expansion of international programming—that has captured the attention of media analysts, investors, and industry competitors alike. As the media landscape continues its tumultuous transition from traditional linear television to a fiercely competitive digital streaming ecosystem, Disney’s capital allocation strategy underscores its determination to maintain market dominance through sheer scale and premium IP acquisition.
Unpacking the Drivers Behind the $26 Billion Investment
A deeper analysis of Disney’s projected $26 billion budget reveals that the financial increase is not a monolithic investment, but rather a targeted strategy anchored by three primary pillars: escalating sports broadcasting rights, the production scheduling of major feature films, and a threefold expansion of international local-language originals for Disney+.
Sports rights represent a massive anchor within this multi-billion-dollar outlay. Disney’s crown jewel in the sports broadcasting sector, the ESPN subsidiary, commands a formidable portfolio of high-profile rights that span major collegiate and professional organizations. These include multi-year agreements with top NCAA conferences, the National Football League (NFL), and the National Basketball Association (NBA).
The financial weight of these sports partnerships is staggering. The landmark NBA media rights renewal, finalized in 2024, locked in a long-term agreement that commands an average annual financial outlay of $2.6 billion. This single contract anchors a significant portion of ESPN’s long-term programming liabilities. Furthermore, Disney’s strategic integration with the NFL is reaching unprecedented heights. In a landmark structural transaction, Disney traded equity in ESPN in exchange for operational control and integration of key league media assets.
The culmination of this partnership will arrive in February 2027, when the cable network broadcasts its first-ever Super Bowl. The historic matchup will also be simultaneously broadcast on the ABC television network, marking the major broadcast network’s triumphant return to America’s most-watched sporting event after a prolonged 20-year absence. Industry observers note that while sports rights command premium pricing, they remain one of the few remaining appointment-viewing catalysts capable of commanding massive, real-time advertising revenues and driving traditional pay-TV bundle retention alongside direct-to-consumer streaming adoption.
Beyond the gridiron and the hardwood, the timing of theatrical feature film production spending is playing a critical role in the fiscal 2027 figures. As the theatrical marketplace continues its post-pandemic stabilization, Disney’s cinematic output across its Marvel Studios, Pixar Animation Studios, Walt Disney Animation Studios, and Lucasfilm divisions requires sustained upfront capital investment years in advance of box office returns. The projected 9% year-over-year increase reflects the cyclical nature of tentpole blockbuster production cycles, ensuring a steady, reliable pipeline of cinematic events for both theatrical exhibition windows and subsequent streaming premieres.
The Global Battleground: Tripling International Originals
While sports and blockbuster cinema remain foundational to Disney’s business model, the company’s digital streaming strategy is undergoing a significant geographical pivot. Alongside domestic sports and film investments, Disney has explicitly flagged international programming as a core catalyst for the expected surge in content expenditure. Company executives confirmed an ambitious plan to roughly triple the delivery volume of international local originals over the next three years.
International programming developed specifically for the Disney+ platform has transformed from a supplementary catalog feature into a critical battleground. In an era where global subscription growth in saturated Western markets has begun to decelerate, acquiring and retaining international subscribers requires hyper-localized content that resonates deeply with regional audiences. Disney is aggressively positioning itself to capture global market share against entrenched streaming behemoths such as Netflix and Amazon Prime Video, as well as newly consolidated market competitors like the newly combined Skydance media entity.
Over the past two years, Disney reports that it has successfully released nine of its most-watched international original titles of all time on the Disney+ platform. The momentum of this international strategy was clearly demonstrated during the fiscal fourth quarter, which ended on October 3. Key regional breakout hits during this reporting window included the second season of A Shop for Killers in the Asia-Pacific region and the musical-comedy phenomenon Soy Luna: Let’s Roll Again in Latin America.
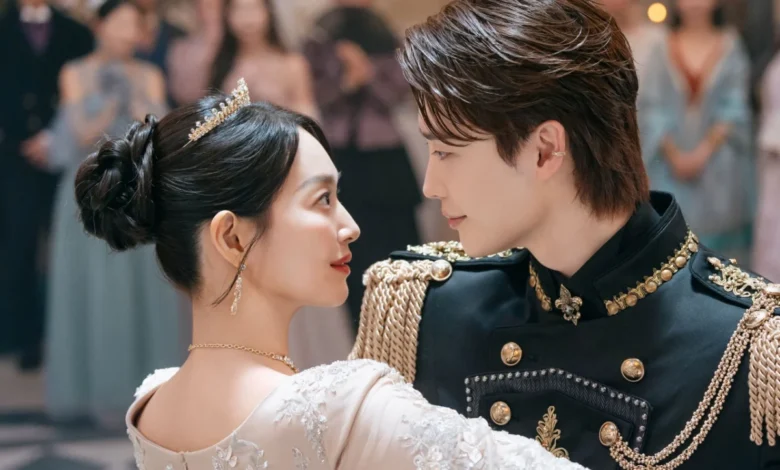
Furthermore, the global appetite for localized content was recently underscored by the breakout success of The Remarried Empress, a South Korean drama series that debuted earlier this month. The series immediately shattered internal engagement metrics, establishing itself as Disney’s largest local original series premiere to date.
Free-to-Air Partnerships as a Competitive Edge
A key differentiator in Disney’s international expansion strategy is its heavy reliance on domestic and regional collaborations rather than operating in an isolated production silo. In its earnings commentary, the company highlighted the strategic advantage provided by its local broadcasting alliances.
“We believe our local free-to-air collaborations are a meaningful competitive advantage — we now have more than 30 across the regions,” Disney stated in its official earnings release. “Local content remains one of the strongest drivers of international subscriber acquisition and engagement, and over the next three years we plan to roughly triple our delivery of local originals.”
By partnering with established free-to-air television networks and local production houses overseas, Disney is able to share production risks, leverage localized marketing pipelines, and tap into established creative talent pools that understand the cultural nuances of specific territories. This localized approach allows Disney+ to function not merely as a repository for Hollywood content, but as a culturally integrated platform that appeals directly to regional households.
Financial Implications and Wall Street Reception
The announcement of a $26 billion cash content spend for fiscal 2027 provides a clear window into executive leadership’s vision for the company’s future. In the immediate wake of the fiscal fourth-quarter earnings release, Wall Street analysts largely praised Disney’s operational discipline. The ability of the company to surpass financial expectations while simultaneously committing to substantial long-term investments indicates that its traditional and streaming segments are generating sufficient cash flow to fund future growth without destabilizing the balance sheet.
However, a $26 billion content outlay also raises the stakes for execution. As production costs rise across the entertainment industry—driven by inflationary pressures, complex visual effects requirements, and competitive talent compensation—Disney will be under continuous pressure from institutional investors to demonstrate clear, measurable returns on these capital investments. The financial success of the upcoming 2027 Super Bowl broadcast, the profitability of the expanded international streaming slate, and the box office performance of its theatrical pipeline will all serve as vital benchmarks against which the wisdom of this capital allocation will be measured.
As Disney navigates the complexities of the modern media ecosystem, its willingness to commit significant financial capital to both blockbuster sports franchises and localized international storytelling demonstrates a comprehensive strategy. By balancing the mass-appeal gravitational pull of traditional sports and tentpole cinema with the targeted, subscriber-driving power of regional international originals, Disney is positioning itself to capture diverse revenue streams across an increasingly fragmented global audience.
Related posts: