Separating Fact From Fiction in the Multi-Billion-Dollar Data Center and AI Infrastructure Boom

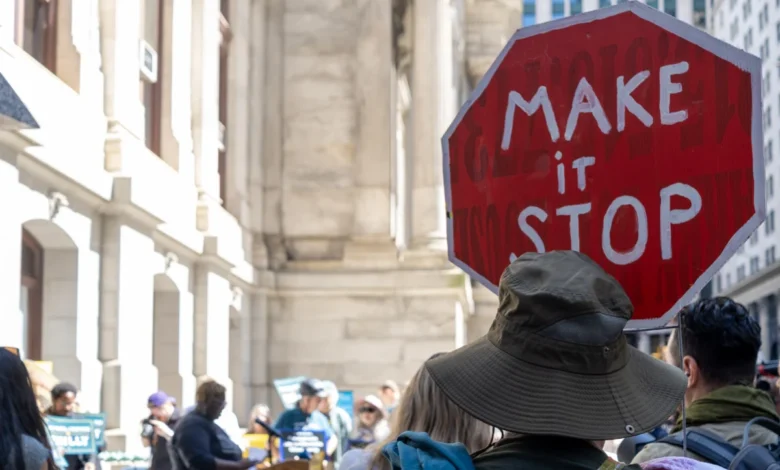
The unprecedented surge in artificial intelligence development has catalyzed a historic expansion in digital infrastructure, with technology giants and specialized developers racing to secure physical space and power for massive new data centers. However, this multi-billion-dollar boom is rapidly colliding with severe real-world constraints. Across the United States, widespread local opposition, complex zoning hurdles, and protracted permitting delays are compounding an even more critical bottleneck: a severe national scarcity of electricity.
Yet, long before these operational, regulatory, and environmental hurdles ever come into play, industry stakeholders face a more fundamental dilemma. A substantial proportion of the data center projects currently announced by corporate entities and real estate developers may never transition from press releases to physical construction. With trillions of dollars in speculative and committed AI infrastructure investments hanging in the balance, financial analysts, utility operators, and policymakers are facing an urgent imperative: separating realistic, viable projects from speculative proposals that exist primarily to drive market sentiment or secure premature financial backing.
The Anatomy of the Data Center Gold Rush
The genesis of the current infrastructure frenzy traces back to the explosive market adoption of generative artificial intelligence models, which require computational power orders of magnitude greater than traditional cloud computing workloads. To train and operate these advanced large language models, major technology firms have committed unprecedented capital expenditures. Consequently, industrial real estate markets have experienced an influx of announcements regarding massive server farms designed to house tens of thousands of specialized graphics processing units.
However, the rapid influx of capital has created a speculative environment reminiscent of historical technology bubbles. Real estate developers, private equity firms, and newly formed infrastructure ventures have rushed to stake claims on strategic parcels of land, announcing multi-gigawatt facilities before securing foundational necessities such as interconnection agreements, water rights, or power purchase contracts. This dynamic has overwhelmed regional transmission organizations and local utility providers, who are left struggling to differentiate between genuine, well-capitalized endeavors and speculative proposals designed to capture early-stage capital or inflate corporate valuations.
Regulatory Pushback and Grid Strain
The friction between soaring digital demands and physical realities has manifested vividly across key regional markets. In Texas, where the deregulated energy market has historically attracted large industrial consumers, state authorities recently took the dramatic step of halting approvals for new data centers amid mounting concerns over grid stability. Governor-led calls for comprehensive statewide audits underscore the growing anxiety that unchecked data center expansion could jeopardize reliable power access for residential and commercial ratepayers.
Simultaneously, the largest power grid in the United States, managed by PJM Interconnection, has reported unprecedented strain as regional utilities grapple with surging interconnection queues. Power grid operators are increasingly forced to re-evaluate how queued projects are managed, pushing back against developers who clutter transmission queues with speculative projects that lack binding financial commitments or realistic operational timelines.
To unpack these complex market dynamics, recent episodes of prominent industry analysis programs, such as TechCrunch’s Equity podcast hosted by journalists Rebecca Bellan and Tim De Chant, have turned to industry insiders. Experts like Brent Nelson, senior managing director of markets and strategy at Ascend Analytics, have emphasized the necessity of rigorous analytical frameworks to vet the viability of announced infrastructure. According to energy and market strategists, evaluating a project’s credibility requires looking past flashy corporate announcements to examine concrete metrics: utility interconnection queue placement, land acquisition status, local zoning approvals, and, crucially, verifiable access to dedicated power generation sources.
Chronology of the Infrastructure Bottleneck
The escalation of the data center viability crisis can be mapped through a series of key regulatory and market milestones over recent years:
- Early 2023: The widespread commercialization of generative artificial intelligence triggers a sudden surge in demand for high-density computational facilities, prompting developers to announce speculative campus builds across North America.
- March 2026: Financial analysts begin highlighting energy technology as the premier investment vehicle for the AI era, as traditional software and hardware investments stall due to physical infrastructure limitations.
- May 2026: System operators within the largest U.S. power grid formally warn regulators that artificial intelligence workloads are pushing regional transmission networks to their limits, triggering widespread stakeholder dissatisfaction and calls for stricter oversight.
- August 2026: State-level intervention reaches a turning point when regulatory bodies in Texas halt the acceptance of new data center applications, ordering comprehensive audits to protect the state’s power grid from overextension.
- Fall 2026: Industry experts and specialized analytics firms increase focus on weeding out speculative projects, introducing stricter criteria for grid interconnection and separating capitalized developers from speculative land bankers.
Analyzing Viability: What Separates Reality From Speculation?
In evaluating the flood of announcements surrounding new artificial intelligence data centers, industry analysts point to several distinct indicators that separate viable projects from speculative ventures.
The primary differentiator is the status of the project within regional transmission organization (RTO) or independent system operator (ISO) interconnection queues. A project that has merely announced its intent to build in a specific county holds vastly different prospects than one that has completed system impact studies and secured formal transmission service agreements. Furthermore, the nature of the power source is paramount. Because municipal grids cannot absorb multi-hundred-megawatt loads without significant infrastructure upgrades, viable projects increasingly rely on co-location agreements with existing power plants, dedicated renewable energy portfolios, or behind-the-meter generation assets, including advanced nuclear or natural gas solutions.
Local political and regulatory alignment also serves as a critical filter. Data centers are notoriously resource-intensive, consuming massive quantities of water for cooling and drawing continuous baseload electricity that can strain local utility pricing. Consequently, projects lacking proactive community engagement, proper zoning designations, and local government support frequently encounter protracted legal challenges and municipal moratoriums that stall development indefinitely.
Economic and Strategic Implications
The ongoing filtration of speculative data center projects carries profound implications for the broader technology and energy sectors. For institutional investors and venture capitalists, the shift toward rigorous project vetting reduces systemic risk, ensuring that capital is directed toward sustainable infrastructure rather than inflated real estate plays.
For the energy sector, the recalibration of data center pipelines provides much-needed breathing room for utilities and grid operators striving to modernize transmission infrastructure without triggering reliability crises or exorbitant rate hikes for everyday consumers. However, it also accelerates a race among major technology enterprises to secure proprietary clean energy sources, fundamentally altering corporate procurement strategies and reshaping the intersection of big tech and national energy policy.
Ultimately, while the data center boom remains a defining economic trend of the artificial intelligence era, the market is undergoing a painful yet necessary maturation. As regulatory scrutiny tightens and analytical frameworks improve, the industry is shifting away from speculative announcements toward a more disciplined, resource-conscious approach to physical infrastructure development.