Air cargo spot rates continue a modest downward trend as market stabilization takes hold in the third quarter of 2026

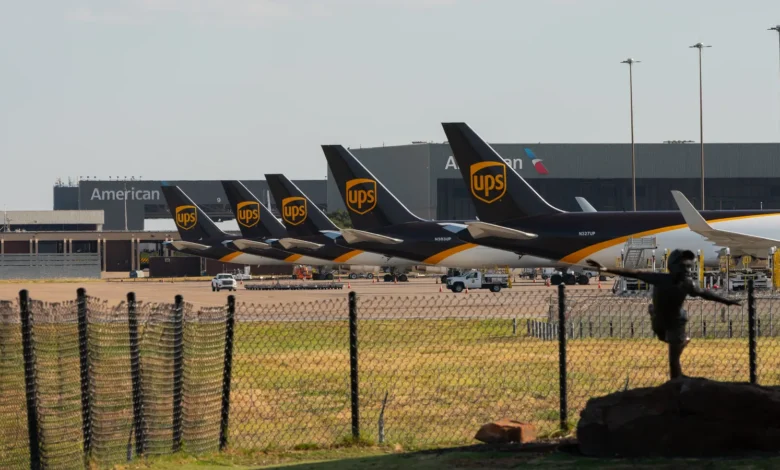
The global air freight market has entered a period of measured cooling, marking the third consecutive month of decline in price growth for spot rates. According to the latest data from logistics intelligence firm Xeneta, the industry is experiencing a slow descent from the peaks observed in May 2026. While shippers are actively seeking to capitalize on this downward trajectory to alleviate budgetary pressures, the market remains characterized by a structural imbalance that prevents a rapid collapse in costs. As of August 2026, the global average air cargo spot rate settled at $3.13 per kilogram—a figure that, while down 3% month-over-month, remains 24% higher than the same period in 2025.
The Dynamics of a Seller’s Market
Niall van de Wouw, a key analyst at Xeneta, suggests that while the downward trend offers a semblance of relief for supply chain managers, the underlying conditions of the market remain firmly in favor of the carriers. "Shippers are looking to push rate levels down because the higher year-over-year costs are having a significant impact on annual budgets," van de Wouw noted. However, he cautioned that the expected decline is unlikely to accelerate.
The market is currently caught between two opposing forces: a cooling effect driven by seasonal capacity shifts and a persistent demand floor that keeps rates elevated. Despite the 3% monthly dip, the global dynamic load factor—a critical metric assessing the utilization of cargo space relative to available capacity—rose by three percentage points to 61% in August. This suggests that while rates are softening, the physical volume of cargo being moved remains robust.
A Chronology of the 2026 Air Freight Landscape
The current state of the air cargo sector is the culmination of several months of volatility that began in early 2026. The industry entered the year with cautious optimism, following a 2025 performance that was marked by significant disruption and inventory restocking cycles.
- February 2026: Air cargo corridors began to show divergence. The surge in AI-related hardware shipments began to create bottlenecks on routes from Northeast and Southeast Asia to North America.
- May 2026: Market rates reached their annual peak, driven by a confluence of rising jet fuel costs and strong e-commerce demand.
- June–August 2026: A period of "controlled cooling" emerged. As passenger travel increased during the summer months, the addition of belly capacity on commercial flights provided some relief to the market, though this was largely offset by rising jet fuel prices.
- September 2026: Current data confirms that the momentum of the decline is slowing, leading to what analysts describe as "small steps" in price adjustments rather than a broad-based crash.
Regional Divergence and Trade Lane Analysis
The global air freight market is not a monolith, and current data highlights a stark contrast between trade lanes based on regional supply and demand drivers.
On the Transpacific trade lane, the impact of the artificial intelligence boom remains the dominant narrative. High-value, time-sensitive shipments of semiconductors and data center hardware have kept demand high. Consequently, spot rates from Northeast and Southeast Asia to North America remain elevated, showing increases of 36% and 34%, respectively, compared to the week starting February 23, 2026. These lanes have become a "seller’s paradise," where the specialized nature of the cargo allows carriers to maintain premium pricing despite broader market cooling.
Conversely, the Transatlantic corridor tells a different story. The influx of seasonal passenger belly capacity—as airlines increase flight frequencies to accommodate summer tourism—has provided a buffer against rate spikes. While rates on this route firmed up slightly by 2% month-over-month in August, they remain 25% lower than the levels seen in late February. This disparity underscores the importance of aircraft type and route density in determining global air freight pricing.

The Role of Jet Fuel and Operational Costs
A critical, often overlooked variable in the current price index is the cost of aviation fuel. Over the past few weeks, jet fuel prices have exhibited a bullish trend, effectively putting a floor under how low spot rates can go. Even as shippers demand lower prices, carriers are faced with higher operational expenditures, preventing them from aggressively slashing rates to win volume.
This "cost-floor" effect is why the decline in rates has been described as a "descent in small steps." Logistics managers are increasingly turning to short-term capacity purchases to navigate this uncertainty. By avoiding long-term fixed contracts in a falling market, shippers are attempting to capture the downward trend in real-time, though this strategy leaves them vulnerable to sudden spikes if global fuel prices or demand surges occur.
Broad Economic Implications and Forecasts
Looking ahead, the outlook for the remainder of 2026 remains cautiously optimistic. The global air cargo market is currently on track for a 4% growth rate in total volume for the year, a projection that exceeds the more conservative estimates made at the close of 2025. This resilience is a testament to the essential role of air freight in global supply chains, particularly for sectors that cannot afford the lead times associated with ocean shipping.
For many enterprises, the "new normal" of 2026 is defined by a period of relative stability. While the current pricing environment is objectively higher than historical averages, it lacks the chaotic, double-digit monthly fluctuations that characterized the supply chain crises of the recent past. This stability, according to industry observers, is a development to be celebrated.

"The market has been performing at a relatively stable level for several months," van de Wouw observed. "Yes, of course, shippers want to pay less for capacity, but versus some of the major disruptions we have seen, a period of relative calm should be celebrated, and the resilience of air freight appreciated."
Strategic Outlook for Shippers
As the industry moves into the final quarter of the year, several factors remain to be monitored:
- Inventory Management: If the 6% year-over-year growth in cargo volumes continues, shippers may be forced to secure capacity earlier than planned to avoid the year-end peak season rush.
- Capacity Utilization: The 61% global dynamic load factor indicates that there is still room for optimization. If demand growth outpaces capacity additions in the coming months, spot rates could stabilize or even see a temporary reversal.
- Geopolitical and Economic Headwinds: As with any global logistics sector, air freight remains sensitive to fuel price fluctuations and potential trade policy shifts that could impact the movement of goods between major economic blocs.
Ultimately, the air freight sector is navigating a delicate balancing act. Shippers are successfully leveraging short-term procurement strategies to manage costs, but they remain beholden to the fundamental realities of supply constraints and the high cost of energy. The trend suggests that while the "easy" wins in rate reductions may have been realized, the market is unlikely to return to the ultra-low cost environment of the pre-2020 era. Instead, businesses should prepare for a landscape of sustained, albeit slightly moderating, costs as the year concludes.