Target Corp. Third-Quarter Earnings Reveal a Fragile Turnaround as CEO Michael Fiddelke Navigates Grocery Gains and Apparel Struggles

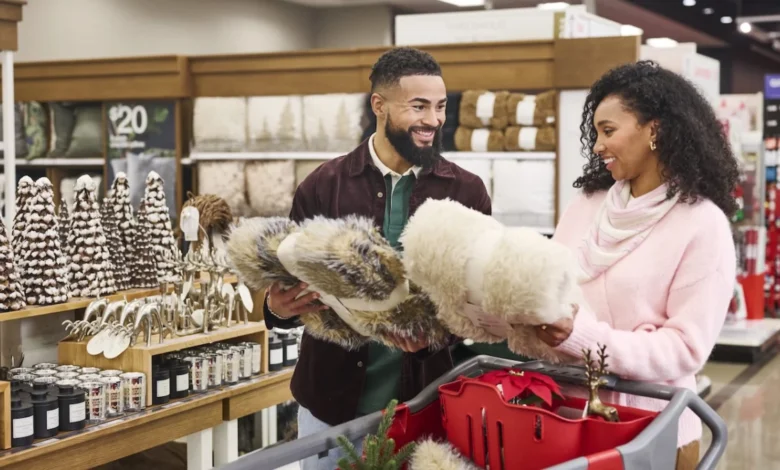
Target Corporation’s third-quarter earnings report, released on Wednesday, offered investors a measure of reassurance that the retail giant is finally finding its operational footing under the leadership of Chief Executive Officer Michael Fiddelke, who assumed the role in February. For the quarter, Target posted a comparable sales increase of 5.6%, driven largely by a robust 5% growth in comparable store traffic.
However, despite the initial positive market reaction and a broad sigh of relief from Wall Street, retail analysts have been quick to temper their enthusiasm. Longtime retail consultant and Confluencer Commerce founder Bryan Gildenberg noted that while the recent figures represent a step forward, they must be contextualized against a challenging backdrop. According to Gildenberg, Target endured a difficult operational period through much of 2025. When measured against the baseline of 2024—a more reliable barometer of underlying business health—the company registered a modest 2.9% comparable sales growth, an improvement from the 1.9% increase recorded in the second quarter.
That is better and not bad, Gildenberg observed, evaluating the trajectory of the big-box retailer. But in an inflationary environment, 2.9% comps are not going to put you in the retail hall of fame.
The Anatomy of Growth: Food and Beauty Drive Traffic
The primary engine behind Target’s traffic recovery has been its renewed focus on the food and beverage category. Company executives revealed that food and beverage sales expanded by nearly 7% year-over-year during the quarter. This momentum was supported by a massive product rollout that saw the introduction of roughly 2,000 new items in the category.
Gildenberg pointed out that Target’s strategic pivot in grocery has played a pivotal role in driving foot traffic, even if it has not yet translated into larger basket sizes. In their journey to fix things, Target seems to have fixed food a little bit faster than they have fixed apparel, he explained. And when you unpack the algebra, you have a store that’s getting more frequent trips, but not necessarily bigger baskets.
At the same time, the beauty sector emerged as another major growth driver, posting a year-over-year increase of over 9%. This surge coincided with Target’s strategic evolution of its cosmetics and skincare presentation. Following its earlier shop-in-shop collaboration era with Ulta Beauty, Target has begun transitioning hundreds of locations to its proprietary Target Beauty Studio layout. This new format has allowed the retailer to introduce 90 new brands, heavily leaning into distinctive, culturally relevant lines, including viral TikTok sensations and trending K-beauty products.
Persistent Headwinds in Fashion and Home Goods
While grocery and beauty have provided vital momentum, Target leadership has been candid about structural challenges persisting in its fashion and home goods divisions. Cara Sylvester, Target’s Executive Vice President and Chief Commercial Officer, addressed the difficulties head-on during the earnings call, characterizing the apparel hurdles as significantly more complex.
Sylvester acknowledged that the company’s apparel assortment and overall value proposition had become overly complex, plagued by inconsistencies across sizing, fabric integrity, and quality control. In response to these missteps, Target has implemented targeted leadership changes within the fashion division, drastically reduced style counts, and lowered price points across hundreds of everyday items.
The home goods category presents an even longer-term strategic puzzle. Having failed to meaningfully reinvent its home product lines to counter the aggressive market dominance of competitors like HomeGoods, Target executives conceded that rehabilitating the home division will require a multi-year turnaround effort.
Decoding Target’s Grocery Strategy: Beyond the Walmart Rivalry
Market observers frequently frame Target’s grocery business as a direct battleground with retail titan Walmart. However, retail analysts suggest this comparison overlooks fundamental geographic and demographic realities.
An overwhelming percentage of Target’s retail footprint is concentrated in states where Walmart does not maintain heavy market saturation. For instance, California accounts for approximately a quarter of Target’s total business, and Walmart is not its primary competitor in that market. Instead, Target’s true grocery competitors are major regional supermarket chains such as Kroger and Albertsons, which hold dominant market shares in key metropolitan areas across California, Florida, and Texas.
Furthermore, Target occupies a unique psychological space relative to wholesale clubs like Costco. Rather than attempting to serve as a primary destination supermarket—a strategy analysts argue forces Target to compete on razor-thin margins against low-cost grocery models—Target functions most effectively as a complementary, secondary shopping trip. By curating unique, innovative food products that wholesale clubs typically omit, Target successfully captures consumers looking for specialized items.
This symbiotic relationship mirrors the dynamic between Costco and Trader Joe’s, where consumers frequent both locations to satisfy different shopping missions. Target’s expansion of its Good & Gather private-label brand has further reinforced this strategy, providing basic commodities in premium packaging that command healthier profit margins while appealing to value-conscious shoppers.
The Evolution of Target’s Beauty and Fashion Identity
The recalibration of Target’s beauty strategy highlights a broader corporate effort to align retail execution with the company’s historical design DNA. The phased removal of the Ulta shop-in-shop concept in favor of the independent Target Beauty Studio format has granted the retailer greater merchandising flexibility.
By eliminating brand overlap and expanding floor space dedicated to emerging independent and international beauty labels, Target has transformed its beauty aisles into a destination for discovery. Retail experts note that this rotational merchandising approach—frequently updating assortments to feature trending products—utilizes the same operational rhythm that historically made Target successful in fashion.
In apparel, however, the road to recovery is more precarious. The rise of fast-fashion alternatives, secondary thrift culture, and the explosive growth of online direct-to-consumer value brands like Quince have fundamentally altered the landscape of affordable style. Target’s recent collaborations, such as the Picolette line for children designed in partnership with Olivia Culpo, offer a glimpse into a potential path forward. By marrying fashionable styling details with accessible price points, Target is attempting to carve out a distinct identity that bridges the gap between fast fashion and premium quality.
Broader Market Implications and Leadership Outlook
As CEO Michael Fiddelke approaches the one-year mark of his tenure, the third-quarter results suggest that his administration is willing to confront structural operational flaws with transparency. By publicly acknowledging missteps in apparel and home goods while aggressively capitalizing on momentum in food and beauty, Target has laid the groundwork for a more disciplined operational strategy.
Nevertheless, industry analysts emphasize that fiscal year 2026 will serve as the true referendum on Fiddelke’s leadership. With inflationary pressures continuing to influence consumer discretionary spending and intense competition across all retail categories, Target’s ability to harmonize its diverse product offerings will determine whether its current traffic gains translate into sustained, long-term profitability.
Related posts: