Stripe AI Data Reveals Accelerated Growth, Global Reach, and the Shift to Usage-Based Pricing for Next-Generation Tech Startups

The modern architecture of technology startup growth has undergone a radical compression, according to proprietary transactional data released by global payments infrastructure giant Stripe. Analyzing the financial performance and operational behaviors of the fastest-growing artificial intelligence companies worldwide, Stripe executives presented empirical insights that challenge decades-old Silicon Valley playbooks regarding scaling, international expansion, go-to-market strategies, and monetization frameworks.
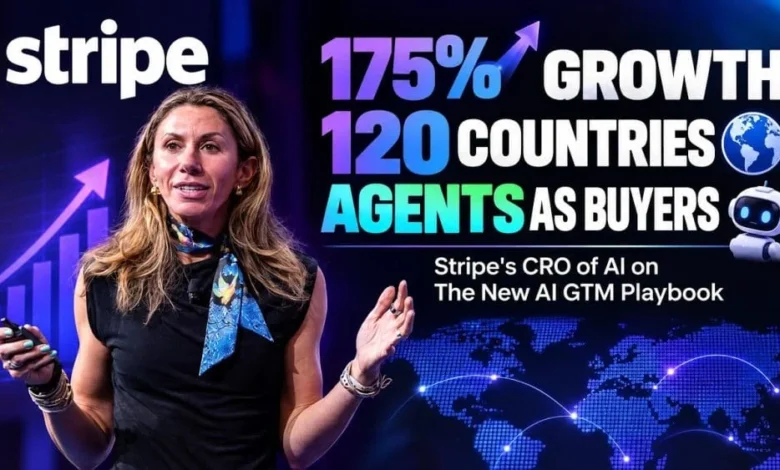
The findings were detailed during a specialized session at the annual SaaStr conference, led by Maia Josebachvili, Chief Revenue Officer of AI at Stripe. Drawing on the unique vantage point of a company that processes payments for a vast majority of the world’s leading artificial intelligence enterprises, Josebachvili outlined how contemporary AI firms are operating at a velocity and scale that far outpaces historical benchmarks established by previous generations of software-as-a-service (SaaS) and cloud computing startups.
Unprecedented Growth Trajectories and Consumer Adoption Metrics
In traditional business-to-business (B2B) markets, revenue growth rates predictably decay as companies scale and encounter the natural friction of larger organizational sizes. However, Stripe’s transactional telemetry reveals an anomalous trend among its top-tier artificial intelligence customers. Rather than experiencing growth deceleration, Stripe’s leading AI cohort expanded by 120% in 2025, a figure that accelerated to an astounding 175% year-over-year growth rate. This dynamic effectively translates to near-tripling revenue performance within a single calendar year, defying conventional economic expectations for maturing tech firms.
Parallel shifts are distinctly visible in consumer-facing artificial intelligence markets. Data compiled from Stripe’s Link checkout network indicates that the absolute count of individual consumers purchasing artificial intelligence products doubled over a twelve-month period, climbing from fewer than 6 million to 14 million active buyers. Furthermore, spending behavior within this demographic has intensified significantly. The top tier of Link buyers now allocates an average of $371 annually toward artificial intelligence products—a notable increase from $140 the previous year. To contextualize this financial commitment, top-tier consumer spending on AI now surpasses the average American household’s combined annual expenditure on internet connectivity, traditional streaming services, and mobile phone bills.
The Shrinking Lifecycle from Concept to Commercialization
The foundational timeline required to transition a software concept into a revenue-generating commercial product has compressed dramatically, catalyzed by the proliferation of developer platforms such as Replit and Vercel alongside agentic coding tools. Historically, launching a digital storefront and securing initial paying customers demanded months of dedicated engineering work, infrastructure setup, and merchant account procurement.
Stripe’s historical benchmarks illustrate this evolution vividly. When Josebachvili founded her first venture, the adventure travel company Urban Escapes, the technological friction of building an online shopping cart was so pronounced that initial customers were instructed to mail physical checks to her Brooklyn apartment. Today, with embedded payment systems natively integrated into modern developer ecosystems, each successive monthly cohort of new ventures achieves its first paid transaction at a faster rate than the preceding one. The current average duration from initial idea inception to processing the first paying customer has plummeted to under six weeks.
Furthermore, macroeconomic indicators validate this surge in entrepreneurial output. Stripe observed a direct 24% month-over-month increase in iOS application releases immediately following the mainstream adoption of agentic coding assistants. Concurrently, new corporate formations—measured by Delaware incorporations—tracked along the exact same upward curve.
A notable demographic shift within this entrepreneurial boom concerns the composition of founding teams. While industry analysts initially hypothesized that AI coding tools would primarily empower non-technical founders by lowering barriers to software development, Stripe’s empirical data reveals a different reality. The share of technical founders actually increased by seven percentage points over a single year. Advanced coding agents have not replaced technical founders; rather, they have supercharged them, enabling a single technical architect to execute tasks in days that previously required an entire engineering department months to deliver.
Early Globalization: Reaching 42 Countries in Year One
Perhaps the most dramatic departure from traditional enterprise software methodology lies in the timeline and geography of international expansion. The legacy B2B playbook dictated a localized, sequential approach: establish domestic product-market fit, dominate the home market, achieve significant scale, and only then establish international operations by hiring a regional general manager in European hubs such as London or Dublin.
Modern artificial intelligence companies have entirely abandoned this sequential model in favor of global-first deployment. Stripe data shows that top AI firms in 2025 successfully penetrated an average of 42 distinct countries within their first year of operation, scaling that footprint to 120 countries by their third year. Emerging economic regions, once considered secondary markets, now register prominently on revenue ledgers; Kazakhstan, for instance, frequently appears among the top revenue-generating territories for these emerging firms.
This geographic dispersion translates into substantial capital. Across the upper echelon of AI companies, an average of 48% of total revenue originates from outside the domestic home market. A prime case study is Gamma, a San Francisco-based productivity software provider that generated $100 million in revenue during its inaugural year, with the vast majority of those funds originating outside the United States.
Geographically, the United States, Japan, and Germany currently lead in absolute AI expenditure on the Stripe network, aligning closely with respective national gross domestic products. However, growth velocity is highest in South Korea, Brazil, and India. This global distribution carries critical operational imperatives; businesses failing to support localized payment methods—such as Pix in Brazil—are systematically forfeiting addressable market share to more adaptable competitors.
The Dominance of Usage-Based and Hybrid Pricing Models
The structural economics of artificial intelligence have likewise forced a fundamental evolution in software pricing architecture. On-premise software historically relied on perpetual, one-time license fees because the underlying code remained static post-installation. The subsequent shift to cloud computing popularized subscription models to account for continuous software updates.
Artificial intelligence introduces a new variable: the utility derived by the end user and the computational cost incurred to service them vary wildly across different customer segments. As Josebachvili noted, a software engineer who initializes a complex batch of autonomous coding agents before sleeping and a consumer utilizing a conversational chatbot as a mobile browser replacement consume drastically different volumes of compute infrastructure while interacting with the same underlying platform. Applying a single, flat subscription fee to such disparate usage profiles is economically unviable.
Consequently, the software industry has rapidly pivoted toward usage-based and hybrid monetization frameworks. Replit serves as a primary example of this transition. After nearly a decade operating as a traditional developer tools provider, the company pivoted upon the mainstream arrival of agentic coding, layering usage credits on top of standard flat-rate subscriptions. This strategic pivot propelled Replit toward a $1 billion revenue run rate, ensuring predictable baseline cash flow via subscriptions while capturing additional value as customer computational consumption scales.
Market-wide adoption of this model has accelerated sharply. Data indicates that two out of every three companies on the Forbes AI50 list now employ some form of usage-based pricing, marking a substantial increase from fewer than 50% during the previous summer. Most of these market leaders favor a hybrid model that couples predictable subscription tiers with variable consumption credits.
Compressing Go-To-Market Motions and Organizational Design
In alignment with global expansion and pricing evolution, artificial intelligence startups are compressing the traditional corporate maturation timeline regarding go-to-market (GTM) strategies. Historically, companies maintained a strict product-led growth (PLG) motion for years before standing up enterprise sales organizations.
Modern AI firms execute these motions concurrently. Cursor, for example, launched as a self-serve platform in 2023, rapidly introduced a sales-led enterprise motion, and successfully captured major enterprise contracts within a fraction of the time historical software firms required. Industry trends now show that early-stage AI founders are routinely hiring Chief Revenue Officers (CROs) within their first year of operation.
However, executing multiple GTM motions simultaneously introduces severe operational complexity. Introducing sales-led enterprise contracts alongside self-serve models and automated agentic purchasing requires unified revenue infrastructure. Companies that assemble billing, taxation, and payment processing tools piecemeal frequently experience critical system friction and data fragmentation as a single customer transitions from a self-serve tier to an enterprise contract, or when automated agents independently provision new features.
Summary of Critical Operational Missteps
Stripe’s analytical framework identifies eight primary missteps that consistently leave revenue on the table for emerging artificial intelligence enterprises:
- Relying on a Single Currency and Payment Method: Limiting checkouts to domestic currencies and card-only payments creates immediate friction. Localized pricing strategies consistently drive an 18% increase in cross-border revenue, with localized payment methods yielding additional conversion gains.
- Delaying International Expansion: Sticking to a domestic-first expansion strategy surrenders international markets in regions like Latin America and Asia to agile competitors before domestic operations are fully optimized.
- Imposing Flat Pricing on Asymmetric Usage: Failing to capture variable compute costs through hybrid subscription and credit models results in unprofitable power users subsidizing low-usage customers, or vice versa.
- Obscuring Usage Metrics Until Invoicing: Presenting consumers with unexpected consumption bills at the end of a billing cycle drives immediate churn. Real-time usage visibility within the product interface is essential for retention.
- Postponing Enterprise Sales Motions: Waiting until year three to establish a dedicated sales team cedes lucrative enterprise accounts to competitors who have already embedded sales personnel within those organizations.
- Operating Fragmented Revenue Stacks: Maintaining separate customer databases, product catalogs, and billing logic for self-serve and enterprise tiers generates systemic accounting errors as accounts graduate between tiers.
- Lacking Defined Account Graduation Paths: The absence of automated, clear rules governing when a self-serve account transitions to an enterprise agreement forces conflicting internal decisions between product and sales teams.
- Ignoring Non-Human Buyers in Documentation and Pricing: With automated agent traffic to technical documentation increasing tenfold and approaching parity with human web traffic, pricing models and documentation must be optimized for machine-readable discovery, evaluation, and activation.
Analytical Implications for the Broader Tech Ecosystem
The empirical data presented by Stripe underscores a fundamental maturation of the artificial intelligence economy. The era of sequential, localized, and strictly subscription-based software scaling has been permanently displaced by parallel execution. The fastest-growing technology companies of the current decade are executing international deployment, enterprise sales motions, hybrid usage monetization, and machine-to-machine commerce simultaneously from their inception. For modern founders, building a resilient enterprise requires abandoning legacy software playbooks in favor of unified revenue architectures capable of absorbing exponential velocity across global markets.
Related posts: