For decades, financial analysts, policymakers, and economists have debated the steady rise of China’s currency on the global stage, often framing the internationalization of the renminbi (RMB) as an existential threat to the supremacy of the United States dollar. However, according to leading geopolitical scholars and economic historians, this narrative fundamentally misunderstands Beijing’s strategic calculus. Heavy is the head that wears the crown, and contrary to popular global belief, China’s leadership has no genuine desire to see the yuan dethrone the dollar as the world’s preeminent reserve currency.
While Beijing has actively pursued the incremental internationalization of its currency—facilitating cross-border payments, establishing bilateral swap lines, and expanding commodity-pricing benchmarks—it remains deeply averse to assuming the structural burdens, economic obligations, and severe domestic policy constraints that come with issuing the global financial system’s primary anchor.
The Structural Trap of Global Currency Dominance
To truly replace the U.S. dollar, a currency must be backed by open, frictionless capital markets, deep liquidity pools, and complete convertibility. For the People’s Republic of China, fulfilling these prerequisites would directly threaten the Chinese Communist Party’s absolute control over domestic capital allocation.
Political elites and state-adjacent actors within China frequently rely on offshore dollar holdings as an institutional hedge against domestic political shifts and policy purges. Opening capital accounts wide enough to support a true global reserve currency would dismantle the financial firewalls that Beijing relies upon to monitor, direct, and restrict capital flows within its borders.
Rather than seeking outright hegemony, Beijing views the promotion of the yuan through a lens of defensive pragmatism. The primary objective is not to rule the global monetary system, but to insulate China from the coercive potential of Washington’s financial weaponization. Following the unprecedented sanctions imposed on Russia in 2022—which effectively locked Moscow out of the SWIFT messaging network and froze hundreds of billions in foreign exchange reserves—Chinese policymakers recognized the acute vulnerability of operating entirely within a dollar-dominated framework.
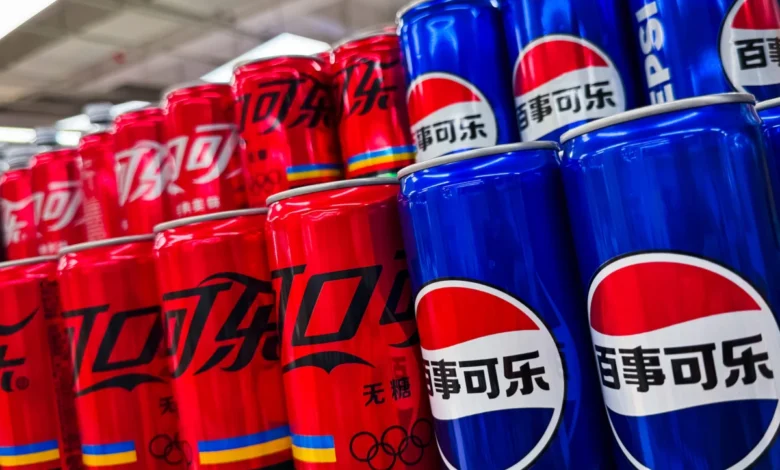
A yuan network that achieves sufficient international utility—even if it permanently plays second fiddle to the dollar—provides a viable alternative pathway for global trade. As Zongyuan Zoe Liu, a senior fellow for China studies at the Council on Foreign Relations, observed in policy analyses, Beijing’s overarching mission is to establish the renminbi as the "Pepsi to the dollar’s Coca-Cola": an entity that may never claim the top market share, but remains robustly serviceable in a pinch and thoroughly capable of keeping the dominant incumbent constrained.
The Mechanics of RMB Internationalization
Despite its reluctance to shoulder global reserve duties, China has methodically expanded the infrastructure required to support non-dollar trade networks. The scale of these initiatives has grown substantially across multiple financial and commercial sectors.
As of mid-2026, the Cross-Border Interbank Payment System (CIPS)—China’s alternative to Western-dominated messaging and clearing systems—boasted 1,829 direct and indirect participants, facilitating transactions across more than 5,200 financial institutions spanning 191 countries. Chinese enterprises now routinely facilitate renminbi settlements with trading partners in more than a hundred nations, focusing heavily on raw materials and commodity markets.
However, operating a true global currency requires far more than basic trade settlement. It encompasses a complex ecosystem comprising five distinct pillars: pricing, financing, risk transfer, and reinvestment, alongside everyday trade invoicing.
Pricing and Invoicing
Historically, Chinese exporters have invoiced transactions in U.S. dollars, converting the proceeds into yuan only upon repatriation. To shift this dynamic, Beijing has championed "China prices"—denominating domestic commodity exchanges in yuan. These efforts have yielded notable success in specific industrial inputs, most notably lithium, a foundational component for modern battery technology and electric vehicles.
Financing and Liquidity
The financing pillar has experienced considerable momentum. Between 2023 and mid-2026, Chinese state and commercial banks more than doubled their yuan-denominated lending portfolios to overseas borrowers. Concurrently, the People’s Bank of China (PBOC) has established currency swap agreements with 32 foreign central banks and monetary authorities, ensuring regional access to renminbi liquidity during periods of market stress.
Risk Transfer and Reinvestment
Progress in risk transfer has been more modest, though incremental steps are visible. State-owned enterprises have increasingly begun settling maritime cargo insurance policies in yuan.
Reinvestment remains the most persistent bottleneck in China’s internationalization strategy. For a currency to achieve reserve status, foreign holders must feel secure parking their capital in domestic assets rather than immediately converting earnings back into dollars or euros. While Beijing has gradually expanded foreign institutional access to onshore Chinese stock and bond markets, unpredictable capital controls continue to deter long-term investment.
By March of this year, foreign investors held a meager 1.6% of the Chinese domestic bond market, a stark contrast to the 27% foreign holding rate observed in U.S. Treasury and debt markets. Without an expansive, highly liquid pool of renminbi-denominated financial assets that can be freely bought and sold without bureaucratic friction, the yuan cannot realistically challenge the structural depth of the U.S. dollar.
The Green Yuan and the Evolution of the Petrodollar
While broad capital market reform remains constrained, China is utilizing a different strategic lever to anchor the yuan in international trade: its absolute dominance over the green energy supply chain.
Just as the historic "petrodollar" arrangement anchored the greenback’s supremacy through global oil trade, China is positioning itself to dictate the terms of trade for critical minerals, photovoltaic equipment, and electrical grid infrastructure. Having consolidated control over the manufacturing and refining ecosystems for clean energy technologies, Beijing possesses the cost advantages and industrial scale necessary to price these hard-to-substitute exports in renminbi.
This commercial leverage lays the foundation for a potential "green yuan," an ecosystem capable of bypassing Western financial architecture for the burgeoning clean-tech economy. This transition is occurring against a backdrop of escalating geopolitical instability in the Middle East, which has cast unprecedented uncertainty over the future of the petrodollar.
The petrodollar system traces its origins to a landmark 1974 agreement wherein Saudi Arabia agreed to price its petroleum exports exclusively in U.S. dollars and reinvest its financial surpluses into American sovereign debt. In exchange, the United States provided an explicit security umbrella, stationing military personnel in the region, supplying advanced defense hardware, and guaranteeing commercial navigation through vital chokepoints like the Strait of Hormuz.
Geopolitical Pressures in the Middle East
Recent military conflicts in the Middle East, including prolonged hostilities involving Iran and regional shipping lanes, have severely tested the durability of these historic security arrangements. Despite sustained naval patrols and military operations, international maritime traffic through the Strait of Hormuz has faced persistent disruptions.
Concurrently, advanced drone and missile capabilities demonstrated by regional actors have exposed vulnerabilities in regional defense infrastructure, prompting renewed risk assessments among Gulf Cooperation Council (GCC) economies. Financial analysts at major institutions, including Deutsche Bank, have warned that sustained security challenges in the Gulf could accelerate the diversification of foreign asset holdings by regional governments.
Market intelligence reports indicating that safe passage through critical Middle Eastern waterways has occasionally been negotiated or facilitated via non-dollar trade arrangements—including oil transactions settled in yuan—underscore a quiet erosion of traditional monetary loyalties. While these developments do not spell the immediate demise of the dollar, they highlight a fragmented global financial architecture where regional hegemons increasingly seek alternatives to U.S.-led clearing mechanisms.
Implications for Global Finance
The realization that Beijing prefers the safety of a secondary global status over the systemic liabilities of currency hegemony fundamentally alters how policymakers in Washington and Brussels must approach economic statecraft.
If China’s primary goal is sanction-proofing its economy rather than overthrowing the global financial order, Western efforts to isolate Beijing through financial penalties face diminishing returns. As long as China maintains its industrial supremacy in critical supply chains and continues expanding bilateral clearing mechanisms like CIPS, a growing bloc of emerging markets will find viable, non-dollar pathways to conduct international commerce.
Ultimately, the global monetary system is shifting away from unipolar dominance toward a multipolar reality. In this evolving landscape, the U.S. dollar will likely retain its crown as the dominant global reserve currency, but it will do so alongside a persistent, institutionalized alternative—the renminbi serving as a structural check on American financial unilateralism.