How Polywood Transformed Outdoor Furniture Retail Through Just-in-Time Ecommerce Strategy

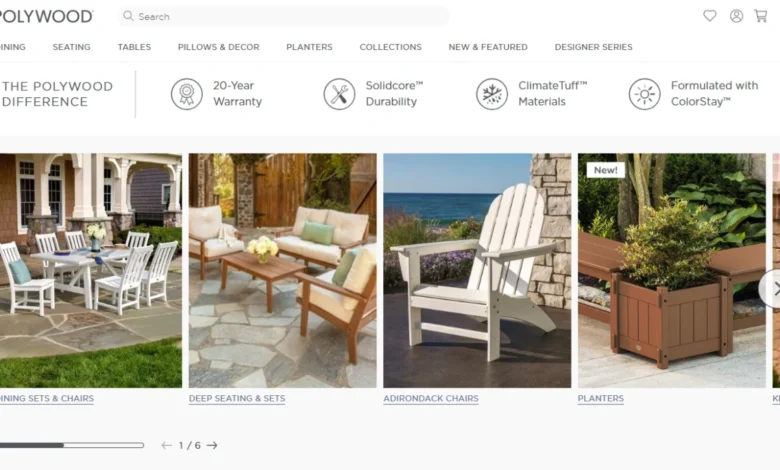
When Ben Spiegel joined the outdoor furniture manufacturer Polywood in 2025, the internal data regarding consumer purchasing behavior challenged his previous experience in the consumer-packaged goods and beauty sectors. While he expected the outdoor furniture industry to rely heavily on traditional brick-and-mortar showrooms, he soon discovered that 75% of the company’s revenue was being driven by its direct-to-consumer (DTC) ecommerce platform. This shift highlights a broader evolution in the home furnishings market, where digital-first strategies are increasingly superseding the traditional limitations of physical retail.
The disconnect between consumer needs and traditional showroom inventory remains a significant pain point in the industry. Spiegel noted that shoppers frequently visit physical locations only to find that the items available do not align with their requirements in terms of color, dimensions, or stock availability. By leveraging a robust digital presence, Polywood has effectively captured the demand of consumers who prefer the precision of online ordering over the inconsistent inventory found at mass merchants or home improvement retailers.
The Mechanics of Just-in-Time Manufacturing
At the heart of Polywood’s operational success is a highly efficient, vertically integrated manufacturing model. Unlike traditional furniture retailers that maintain massive warehouses filled with pre-manufactured goods, Polywood operates on a just-in-time (JIT) production cycle. This model is fundamentally tethered to the digital shopping experience; when a customer completes a purchase on Shopify, the transaction acts as a digital signal that initiates the manufacturing process.
The raw lumber is moved to a machine, extruded, cut to the specific configuration ordered, and prepared for shipping. This "one-piece flow" strategy allows the company to minimize its physical footprint, with Spiegel estimating that the firm keeps no more than 5% of its total inventory on hand at any given time. By manufacturing each piece custom, Polywood provides a massive product assortment without the capital risk associated with holding stagnant inventory. This approach effectively eliminates the "middleman" inefficiency, allowing for a standard delivery window of five to seven business days for custom products.
Chronology of Sales Cycles and Seasonal Volatility
The outdoor furniture market is inherently cyclical, and Polywood’s revenue architecture reflects this reality. Approximately 80% of the company’s annual business is concentrated between the Memorial Day and Labor Day holidays. May serves as a pivotal month, representing a period of high intent as consumers prepare their outdoor living spaces for the summer season.
However, the brand’s digital strategy must adapt to the "second season" phenomenon. While many retailers view the end of the year as a period of cooling for outdoor goods, Polywood has identified a sustained demand from Southern states where the climate allows for outdoor usage well into the winter months. For the company, Black Friday and the broader "Cyber 5" period are not merely about clearing old stock, but rather about capturing the specific, lingering demand of these temperate regions.
The company’s approach to promotional periods is highly calculated. During the Cyber 5, for instance, Polywood avoids aggressive discounting. Instead, the retailer focuses on value-added incentives, such as expedited shipping or the release of exclusive, limited-time products. This strategy maintains the integrity of their price points while acknowledging that the purchase of high-end furniture—often exceeding $1,600 per order—is a planned financial decision rather than an impulsive one.
Consumer Behavior and the "Dream Shopping" Phenomenon
Data from recent promotional events, such as Amazon’s Prime Day in June, provides a clear window into how modern consumers engage with high-ticket furniture. Spiegel observed a noticeable spike in traffic during the event, characterized primarily by "add to cart" activity and intensive comparison shopping rather than immediate conversions.
This behavior indicates that for items with higher price points, the consumer journey has become significantly more complex. During the 2025 Cyber 5 period, the conversion window for Polywood customers extended from the typical seven-day cycle to 10–14 days. Consumers are increasingly engaging in "dream shopping," where they curate their carts and wait for the optimal moment to finalize the transaction, often scouting for flash sales or competitive price matching across multiple tabs.
This "stalking" behavior requires retailers to remain agile with their digital marketing spend. Polywood has had to pivot its conversion optimization strategies, adjusting email marketing, retargeting campaigns, and paid search efforts to remain top-of-mind during these extended deliberation periods. By working with social media influencers to place products in "best of" roundups—such as curated lists for winter yard improvements—the company generates more effective engagement than it does through standard pay-per-click advertising during peak holiday windows.
Economic Implications and Market Sensitivity
The economic environment of the past year has underscored the sensitivity of different consumer segments within the furniture market. Polywood’s data suggests a bifurcation in spending power: while higher-income consumers have largely remained resilient, purchasing higher-priced dining and deep-seating sets, there has been a measurable decline in sales for smaller, lower-priced items.
This trend is a direct reflection of current macroeconomic uncertainty, which disproportionately impacts households with tighter discretionary budgets. The decline in July 4th holiday sales compared to the previous year serves as a case study for this sensitivity. When the broader consumer environment is soft, the "small-ticket" impulse purchases are the first to be pruned from household budgets, whereas the "large-ticket" investment pieces continue to move, albeit with more deliberation.
Strategic Outlook: The Future of DTC Furniture
The implications of Polywood’s operational model are profound for the home furnishings sector. By shifting away from the traditional model of mass inventory and toward a demand-driven, custom-manufacturing framework, the company has mitigated the risks of overproduction and the high costs of warehousing.
Furthermore, the integration of white-label brands provides the company with unique visibility into broader consumer shopping habits. By monitoring when customers fill their baskets across these various labels, Polywood can anticipate market shifts and adjust its digital advertising spend in real-time. This intelligence-led approach to ecommerce is becoming the gold standard for manufacturers looking to survive in an increasingly competitive digital landscape.
As the industry continues to evolve, the reliance on data-driven, just-in-time operations will likely become a prerequisite for success. The challenge for brands in this space will remain the balance between maintaining brand premium status and the constant pressure to offer discounts in a market where consumers are increasingly conditioned to wait for the lowest possible price point.
For Polywood, the path forward involves maintaining the delicate balance of high-frequency digital engagement and the low-frequency, high-value conversion of its core customer base. By continuing to refine its conversion optimization windows and doubling down on regional "second seasons," the company is positioning itself to navigate the complexities of the modern retail environment while maintaining the vertical integration that serves as its primary competitive advantage.
The success of this model demonstrates that even in a traditionally tactile industry, the future of retail is increasingly found in the digital ether, provided that the backend operations are agile enough to meet the promise of "made-to-order" customization at scale. As consumer behavior continues to shift toward longer, more research-intensive buying journeys, firms that can offer both the product quality of a showroom and the data-driven convenience of an ecommerce giant will continue to lead the market.